
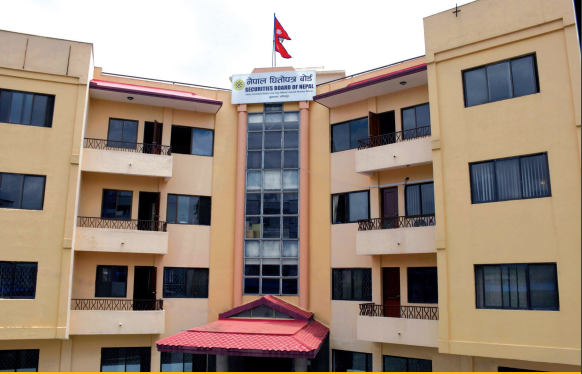
Kathmandu. The Investors Association has given a 6-point recommendation to the Securities Board of Nepal for capital market policy reform.
Nepal Investors Forum, Nepal Capital Market Investors Association and Share Investors Association have submitted their recommendations for immediate policy reforms to make the securities market systematic, transparent, competitive and investor-friendly. The suggestions suggest that timely review of the existing policies and transaction system is necessary to develop Nepal’s capital market in a way that is sustainable, transparent, competitive and increases investor confidence.

In particular, the organizations have
submitted the following suggestions to address the practical problems seen in the free trading of secondary market, sale of shares after large number of promoter locking, structure of IPO and promoter shares, adjustment of price of bonus and right shares, margin trading and settlement of transactions.
15-day early warning provision should be reviewed immediately
}
Secondly, the provision of giving 15 days’ notice before selling shares legally purchased from the market has unduly affected the free trading rights of ordinary investors, the natural demand-supply and liquidity of the market.
- Prior notice is not required in purchase, but the provision of making prior notice mandatory only in sales does not appear to be in accordance with the principle of practical and equal treatment. If information is considered necessary in sales, then on the basis of the same logic, information should also be required in purchase.
- Therefore, the general public should be allowed to freely sell the shares purchased independently in the secondary market.
- should not be unduly quantitative or time-bound in the transactions of ordinary investors.
- In the case of promoter shareholders or in the case of a large number of shares of strategic investors, a prior notice provision can be put in place if more than 5 percent of the shares have to be sold to maintain transparency.
- promoter, limit the current 15 days to 7 days.
In the case of the
Large÷volume sales should be separated from the regular order system and transacted transparently through a separate offer window for sale or block transaction system.TAG_OPEN_li_132
This will not only protect the free trading rights of the general public but will also manage the impact of the sale of large shares in the market.
The structure of IPOs and promoter shares has been reviewed and a price system based on actual demand-supply has been developed{
}
There is a need for timely improvement in the IPO and promoter share structure for determining the real value of the company in the primary market of Nepal and increasing liquidity in the secondary market.
Based on the nature of the company, capital, business and risk
- Policy should be adopted to maintain a minimum share of 30 percent of the IPO.
- Provision should be made to gradually bring other promoter shares into the public business by preserving the share of the main promoter and strategic investor required for the operation of the company.
- Study the lottery distribution system in a transparent manner as per the current system of distribution to institutional investors and mutual investment funds in certain parts of the public issue and to the general public in the remaining part.
In the case of suitable companies, a feasibility study should be conducted to make up to 50 percent of the shares public.TAG_OPEN_li_129
After the IPO listing, arrangements should be made to make the shares that meet certain criteria tradable in the market without unnecessary restrictions.TAG_OPEN_li_128
This will help in creating an orderly market where the price is determined by real demand and supply by reducing the abnormal post-listing price fluctuations and imbalance between promoter-general shares.
Uniformity should be maintained between NEPSE and CDSC in the price adjustment of bonus and right shares{
}
As there is a provision for NEPSE to determine the base price by adjusting the price in a scientific way after the book closure of bonus and right shares, it is necessary to fully integrate the same basis with CDSC’s record and cost price system.
At present, due to the disparity seen in price adjustment and price determination, investors do not have to pay tax if they sell at a profit immediately after price adjustment and have to face tax even if there is no real profit after the listing of bonus shares or right shares.
The CDSC rules should be amended to link the adjusted base price determined by NEPSE after book closure to CDSC’s record system.
- Clear and uniform scientific method should be applied to the cost pricing of bonus shares.
- A system should be made to calculate tax only in the case of actual capital gains.
- } Arrangements should be made to clearly establish the relevant price adjustment and cost basis when the bonus shares come into the account later.
- Separate study on the cost and price adjustment of right shares should be done and necessary new provisions should be introduced.
It will eliminate the disparity between NEPSE, CDSC and tax system and provide a clear, transparent and equitable system to the investors.
Margin arrangements should be applied to margin transactions as per the same criteria and risk
It is a complaint that different securities brokers are practising different interest rates in margin trading. On the other hand, when the range of daily price fluctuations in the market is comparatively large, high debt-based transactions can put investors at high risk.
For example, if an investor buys a stock at a margin during a market rise, on the same day or within a few days, if there is a continuous negative circuit, then a large part of his real investment can be lost in a short period of time.
- The same minimum standards of margin trading should be applied to all brokers.
- High debt ratios should be controlled on high-risk stocks.
- Additional risk management should be provided in case of abnormal market fluctuations.
- Clearly inform investors of the potential profit and loss of margin trading before the transaction.
Different TAG_OPEN_li_121 margin rates should be determined based on the liquidity, price fluctuations and risk of the shares.
This will help maintain stability in the market and indices by reducing the pressure of high debt-based transactions and emergency sales.
T plus two or T plus three transactions and settlement system should be made faster, equal, systematic, secure and technology-friendly
}
The time it takes for the stock and the actual amount of money to be settled after the purchase of the stock can expose investors to additional value in the event of rapid market volatility.
- Investors may have to risk a price that is out of their control if they have a continuous negative circuit before the stock is bought in the market.
- The existing 15 percent should be reduced to 10 percent in the past. This will help to make the capital market more orderly and dynamic by making margin transactions easier and reducing the risk of investors’ risk, deposit and post-purchase payments.
- Direct and automatic coordination between CDSC, NEPSE, brokers and banking system should be enhanced.
- Make the process of settling shares and amounts as fast and secure as possible.
- Prepare to move to a T+1 or shorter clearance system in the future, depending on the technology’s capabilities.
- Develop a system to reduce unnecessary price risk after investors’ transactions.
TAG_OPEN_li_115 Study the feasibility of gradually shortening the existing T plus Two or T Plus Three system.
This will increase the trading capacity of the market, liquidity and investor confidence.
Overall regulatory reforms should be carried out with equal treatment, transparency and investor interest in the market{
}
The above issues are not only individual problems but also related to the structure of the capital market as a whole, investor confidence and market stability.
The purpose of regulation should be to maintain transparency, fairness, risk control and investor protection, not to restrict transactions unnecessarily.
- to ensure the free buying and selling rights of investors,
- Applying the same rules to businesses of the same nature,
- Maintaining transparency in the transactions of large founders,
- Develop a technology-friendly and speedy clearance system,
- Margin and credit management according to market risk,
- }We urge the government to move forward with the overall regulatory reform so that the international practices are only in line with the market structure of Nepal.
Therefore, the Securities Board of Nepal (SEBON) held direct discussions with Nepal Stock Exchange, CDSC, Nepal Rastra Bank, securities brokers, listed companies and investor representatives.TAG_OPEN_li_110
}
}
}
Findings and Requests
Nepal’s capital market needs to be developed not only as a medium for buying and selling shares, but also as an important base for national capital formation, industry expansion, job creation and economic prosperity.
For this, it is necessary to pay equal attention to the real behavior of the market, the risk of investors, the development of technology, international practices and the market structure of Nepal while formulating rules and policies.
The investors’ associations have also urged the government to study the 6-point suggestions with priority and hold necessary discussions and consultations with the stakeholders and investors’ representatives to move ahead with implementable policy reforms in a practical manner.