
The life insurance business is expanding in Nepal. With the increase in the reach of insurance companies, branch network, number of agents and diversity of insurance services, the access to insurance among the general public has also expanded.
According to the Insurance Authority of Nepal, in the financial year 2081. In 1982, the total insurance premium of life insurance was Rs. 182.27 billion. During the same period, the population penetration of life insurance has increased by 39.99 percent. The life insurance sector has invested Rs. 759.66 billion, which shows its importance in the economy. Although these figures are encouraging, the future journey of the life insurance business should not be limited to increasing the size of the business only. The question is not only how much the business has grown, how long it has lasted, how satisfied the agents and insured are and how much it is providing long-term financial security.

Competition is necessary, but what kind of competition?
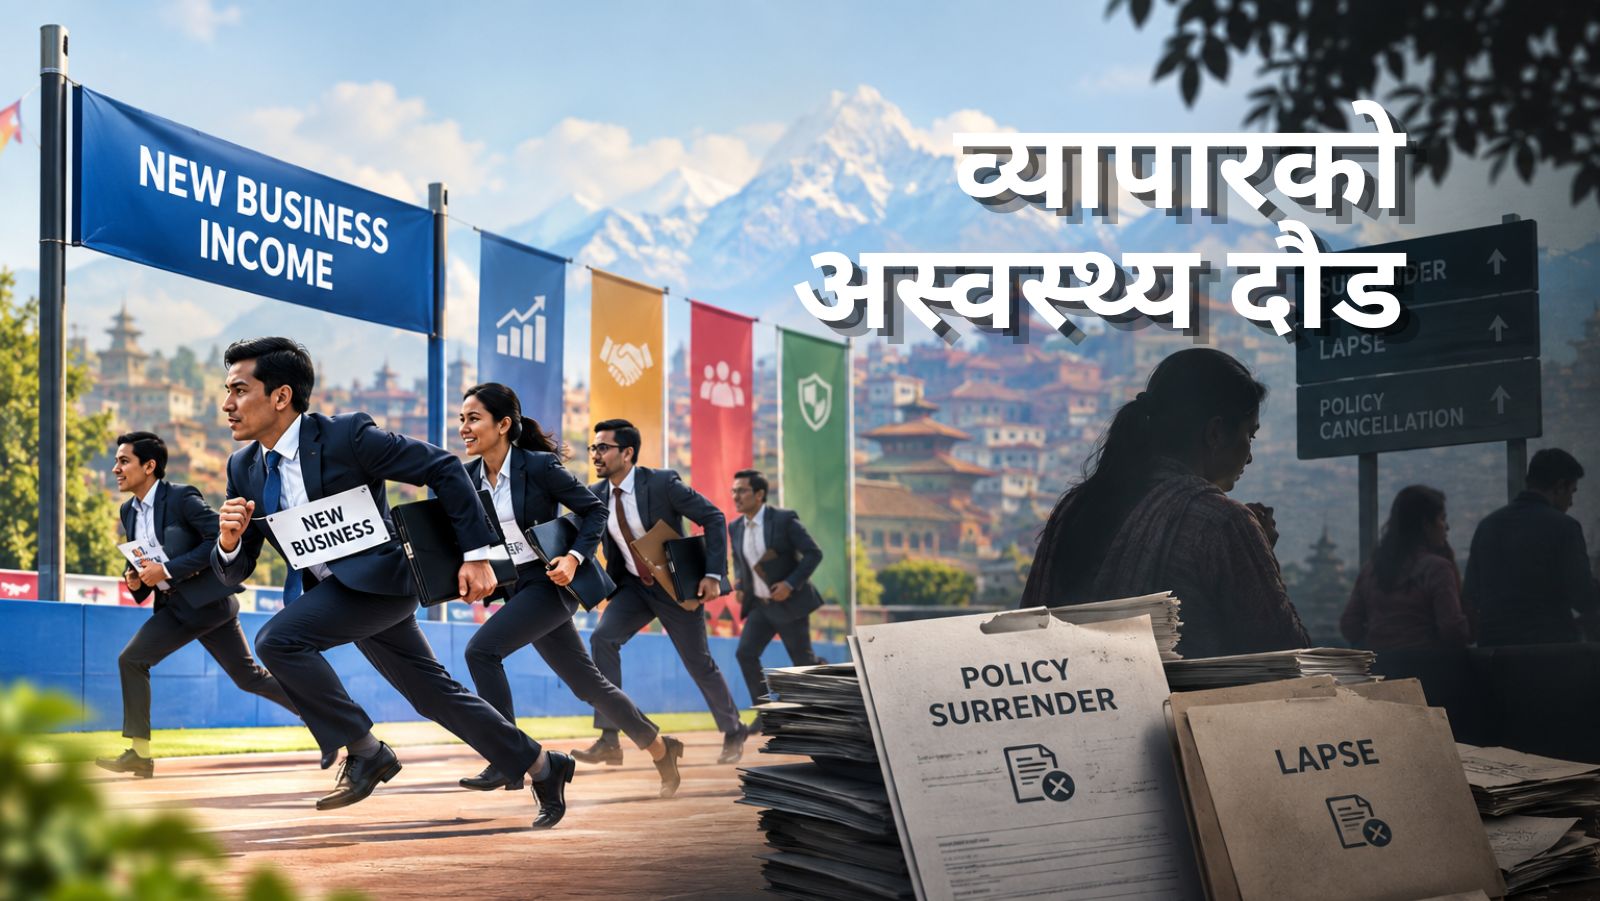
Competition is a natural process of the market economy. Competition motivates companies to develop better services, technology, products and experience of insured and agents. The Insurance Authority’s own objective is to provide quality insurance services through healthy competition by making the insurance business systematic, regulated, competitive and reliable. However, if competition does not focus on creating a new market and improving the quality of service, but if it turns into a race to move the existing insured, agent or business from one company to another, then its long-term impact should be considered. Life insurance is different from many other businesses. It is not just a 1-2 year transaction; It is a financial contract between the insured and the company that can last for decades. Therefore, the real quality of today’s sales can be seen only after many years.
Unhealthy Competition: A Challenge for the Life Insurance Industry
The Insurance Authority itself has identified unhealthy competition among insurers as one of the challenges of the insurance market. In addition, the authority has pointed out that there is a need to improve good governance, risk assessment, market research, claim payment, employee training and other institutional aspects in the life insurance sector. It is not enough to understand it only as a matter of business competition between two companies. The impact of unhealthy competition can gradually reach the entire industry, the company, the employees, the agents, and ultimately the insured.
1. Impact on the overall insurance industry
}
One of the biggest risks of unhealthy competition is that it can undermine the business culture and credibility of the entire industry. If companies focus on pulling each other’s existing businesses rather than creating new markets, the actual expansion of the overall insurance market may slow down. While competition to change companies for a single customer may temporarily change the shape of a company’s business, it does not necessarily lead to the addition of new insurers and expanding insurance access. Similarly, overly goal-oriented competition creates an environment in which quantity-oriented businesses are prioritized over quality businesses. This poses a challenge to policy continuity, insured satisfaction, claims experience, and long-term business stability. In the long run, such a trend also increases the risk of life insurance being perceived only as a commodity of sale rather than a means of financial security.
2. Impact on Companies
}
Unhealthy competition increases the company’s costs, risks, and managerial pressures. As the pressure mounts to maintain or increase its market share, companies may have to spend more than expected in areas such as branch expansion, sales incentives, agent management, publicity, and other areas. However, if quality and long-term business is not created according to the expenses, it will have an impact on the financial performance of the company. On the other hand, giving too much importance to the immediate business goals can overshadow long-term foundations such as risk assessment, market research, product development, employee development, customer service and corporate governance. The Insurance Authority has also noted that the on-the-ground monitoring of life insurance companies has found weaknesses in financial and medical risk assessment, lack of adequate market research, lack of adequate investment in employee training, and challenges in the effective implementation of claims payment arrangements. Therefore, the true competitiveness of a company should depend not only on the business but also on its ability to build a sustainable business with risk control.
3. Impact on Employees
}
Unhealthy competition also has a direct impact on the working environment of the employees. When the priorities of the organization are constantly focused on short-term goals, immediate business and market pressures, then the employees can be subjected to excessive workload, the stress of the goal, and the psychological pressure to show consistent results. This develops a culture of prioritizing immediate results over the creativity and long-term thinking of the employees.
Similarly, if the competition to attract employees among companies is not based on healthy talent development but focuses only on facilities or immediate benefits, then there is instability in organizational knowledge, experience and leadership development. As a result, challenges arise in the long-term commitment of employees, institutional culture and successor leadership development.
4. Effect on the agent
}
The impact of unhealthy competition in the life insurance business is most clearly seen in the agent structure. If the success of the agent is tied to the creation of new insured, identification of the needs of the insured, quality service, and long-term business, then it has a negative impact on the business culture of the agent. Unfair interference in the business of another company, attempts to relocate the insured or agent unnecessarily, the practice of refunding commissions or offering illegal inducements undermines the trust and professional dignity of the agent. In Nepal, the Agent Code of Conduct prohibits such unhealthy competitive practices. This risks shifting the agent’s attention to immediate business rather than understanding the needs of the client and building long-term relationships. Ultimately, this has an impact on the agent’s productivity, long-term durability, and professional reputation.
5. Impact on the Insured{
}
The most vulnerable impact of unhealthy competition is that the insured has to bear the brunt of it. Since life insurance is a long-term financial contract, a sale made without misinformation, incomplete information or understanding the real needs of the insured can lead to serious problems in the future. Under the pressure of short-term profit or sale, over-the-top or duplicate policy, attracting the old policy to a new policy without realizing its actual pros and cons, and failure to provide adequate information or information about the terms, features, exceptions and obligations of the policy, affect the financial interests of the insured. Such practices can lead to problems in policy continuity, premature surrender, and dissatisfaction among the insured and there may be a gap between the policy provisions and the insured’s expectations at the time of claim. As a result, financial loss can be accompanied by mental anguish and unnecessary disputes. In addition, unnecessary hassles, delays or procedural complications in the claim and service process can lead to additional hardship for the insured. The direct impact of this is not limited to the insured; Such experiences gradually weaken the public trust in the insurance business and affect the reputation of the entire insurance sector. Therefore, the main question today is not whether competition is necessary or not, but what should be the competition.
New Basis of Competition in Life Insurance Business
Competition is necessary in the life insurance business, but its basis and purpose should be clear. Healthy competition puts the development of the entire insurance business and the interests of the insured at the center of not only the companies. Now the time has come to change the basis of competition. The following needs to be done to increase the basis of healthy competition in the life insurance business. The main basis of healthy competition is as follows.
Quality and Sustainability of Business
A new policy and a first-year insurance premium should not be the only criterion for the success of the business. Continuity, renewal, dedication and long-term contribution of the policy should also be linked to the quality of the business.
New field of possibility and creation of new insured
Instead of expanding the business by shifting the same insured or agent from one company to another, creating new insurers by reaching out to the underserved class and region should be the main basis of competition.
Agent Professional Development
Not only to increase the number of agents, but also to develop their knowledge, skills, ethics, productivity and professional capacity. Agents need to be developed not only as insurance salesmen but also as advisors for financial security and risk management of the insured. Agents need to be made proficient and competent in technical and non-technical subjects through professional training.
Transparent and Responsible Sales System
Selling life insurance should not only be taken as a process of issuance of insurance but also as a means of establishing a long-term relationship of trust and accountability with the insured. While selling insurance, along with the benefits of insurance, the premium, term of insurance, risk, exceptions, surrender, condition of inactivation of the insurance policy and the provisions related to the claim should be explained clearly and simply. There is a need to develop a professional culture of providing insurance services with appropriate counseling, keeping in mind the needs, financial capacity and long-term well-being of the insured. Instead of the tendency to change the old insurance policy unnecessarily or over-insure, priority should be given to the actual need identification, appropriate solution and the process of selling insurance responsibly.
Strengthened risk assessment and professional discipline
Weakening risk assessment under pressure to meet business goals can be challenging in the long run. Therefore, with business expansion, accurate risk identification, proper assessment and effective risk management should be made an important basis of competition. In risk assessment, it is necessary to maintain professional discipline and give priority to quality and sustainable business growth.
Customer Service & Trust
The real value of life insurance is not seen at the time of sale but at the time of need. Therefore, maintaining the trust of the agent and the insured through fast, simple, transparent and reliable service and claim payment should be an important basis of competition.
Identifiable due to inactive and dedicated insurance policy
The question of why the insurance policy became inoperative or surrendered should be seriously analyzed. There is a need to identify the cause and improve the product, the process of selling the policy, the education of the agent and the insured, and the after-insurance service.
Technology, Innovation, and Marketability
}
Competition should be focused on simple, useful and technology-friendly insurance services and product development as per the changing needs, lifestyle and economic conditions of the customers.
Staff and Institutional Capacity Development
Skilled manpower and strong institutional capacity are indispensable for the sustainable development of the life insurance business. Opportunities for continuous training, learning and capacity development should be ensured to enhance the knowledge, skills, leadership skills and professional skills of the employees. Only accountability based on merit, fair opportunities, clear performance standards and leadership development can further strengthen the institutional capacity and work culture. Competent manpower and strong institutional capacity will ensure quality business, healthy competition and long-term institutional stability.
(The writer is with Himalayan Life.) )