
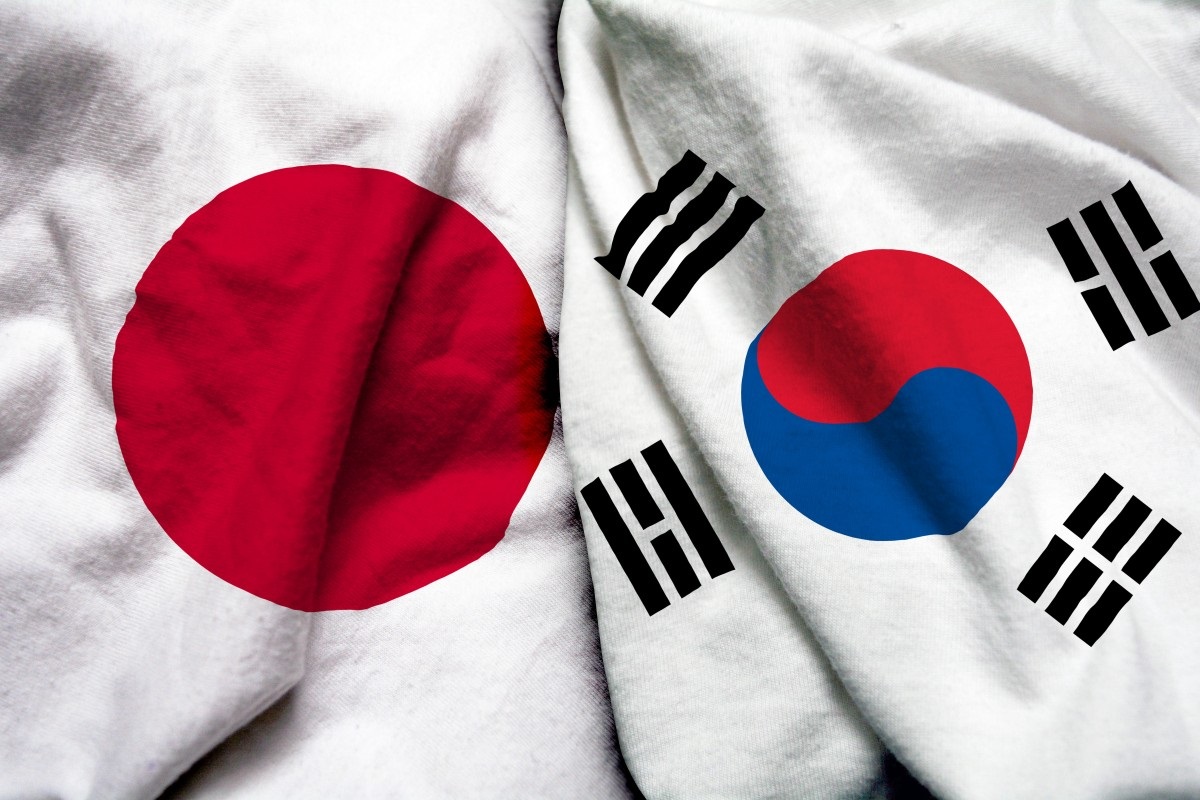
Kathmandu. Japan and South Korea present two mature but distinct opportunities for insurance companies in developed Asian markets. One market is large in terms of total premium volume and ranks in the top five globally. While the other offers higher insurance density, better penetration relative to GDP, and strong medium-term growth prospects.
According to data from the Swiss Re Institute, total insurance premiums in Japan are projected to reach about $327 billion in 2025. This puts Japan in fifth place globally and accounts for about 3.9 percent of the world’s total insurance volume.

In Japan, life insurance, backed by savings and annuity products, prevails in a high-interest rate environment. Non-life insurance premiums comprise a large portion of motor insurance. Represent a small but large share of the total market.
In the same year, South Korea was in ninth place with a premium of about $186 billion (Allianz estimates this figure at about $176 billion). Thus, in terms of total size, Japan’s market is almost twice as large as South Korea’s.
The development paths of the two countries are different. Swiss Rico estimates that real premium growth in Japan will be much slower until 2026 (about 0.3 percent for both life and nonlife), then stabilize around a long-term average of 0.6 percent to 0.9 percent. The aging and declining population there has limited demand for traditional protection products. However, savings products and some specialized non-life insurance products (such as liability and cyber insurance) remain strong. Growth prospects in South Korea are strong.
Allianz estimates that property and casualty premiums will grow by an average of 4.9 percent and life insurance premiums by 4.4 percent by 2036. That would bring the total market to about $290 billion.
Local estimates from the Korea Insurance Research Institute predict moderate growth of about 2.3 percent in 2026 after strong growth in recent years.
South Korea has a strong position in terms of insurance penetration and density. In Japan, insurance premiums were about 7.4 percent of GDP in 2025 and insurance spending per capita was about $2,450.
In South Korea, insurance penetration ranges from 9.4 to 9.8 percent of GDP. This is one of the highest rates in Asia. The average per capita spending is about $3,400.
Both markets are highly developed by global standards. However, South Korea’s high proportion reflects households’ strong engagement with life and non-life insurance coverage.
Japan benefits from its large size, well-established regulatory framework, and strong demand for retirement, savings, and disaster products. This market is constantly adapting to inflation, high interest rates, and a price-based solution system. Challenges include demographic barriers, slow growth in property insurance following recent rate changes due to outbreaks, and low real growth in the motor insurance sector. The distribution system is very mature. However, it is now under pressure to innovate to address new risks such as digital channels and cybersecurity.
South Korea benefits from high insurance penetration, strong demographic support for health and pension products, and immense potential for expansion into the long-term and liability insurance sectors. Mandatory and voluntary motor insurance coverage remains important. While general insurance agencies have expanded rapidly.
Margins are under pressure due to intense competition, rising claims in motor insurance, inflation and the impact of IFRS 17 implementation on contract service margins. Insurance companies will also have to pay attention to household debt levels and real estate conditions.
According to Swiss Rica, the overall insurance industry is experiencing a slowdown. This will affect both markets. Global real premium growth is projected to be 1.3 percent in 2026 and 1.6 percent in 2027. Against this backdrop, Japan has a large demand base and a highly developed product range. Whereas South Korea has a high insurance density and penetration. There are good percentage growth prospects in the next decade.
Insurance companies should compare Japan’s large size and maturity to South Korea’s intensive insurance penetration and rapid expansion. None of these pathways automatically guarantee higher profits. Long-term returns will ultimately depend on underwriting discipline, correct pricing, distribution financial efficiency, claims experience, and capital management. -Agency